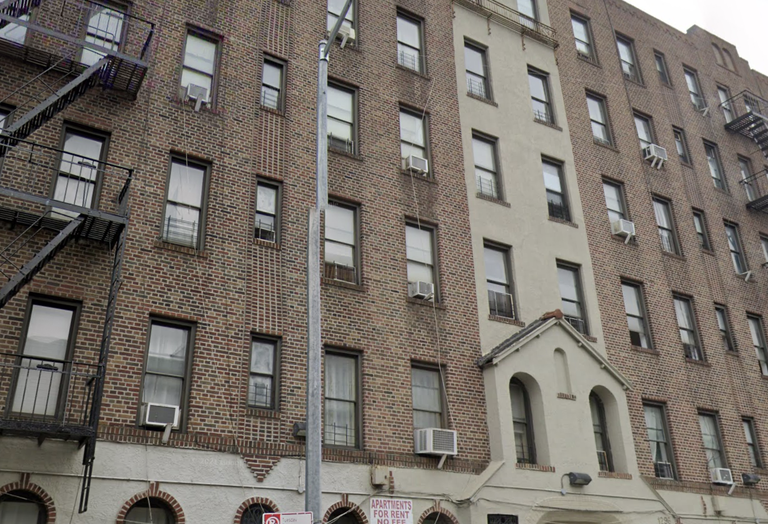
Real estate owner and operator Summit Properties USA agreed to buy a portfolio of more than 5,000 New York City apartments placed into bankruptcy by Pinnacle Group, according to new court filings.
Stalking horse bidder Summit Gold Inc. offered $451M to take over the properties and their leases.
If the portfolio's lender, Flagstar Bank, chooses to forgo financing the purchase price, the original offer will automatically be lowered to $420M, the filing states. An auction will be held on Jan. 8, if necessary.
Other bidders are approaching to buy the units: the tenants themselves.
The bidding process started Nov. 21, and tenants want in. A group of residents at 40 of the 93 properties has been exploring ways to buy their homes and get them serviced. The properties have fallen into disrepair, with many violating NYC housing code by not having electricity and being exposed to mold and mice.
Summit buying the properties means the tenants will have until Jan. 11 to file an objection to the sale with the bankruptcy court if they want to move forward with the ownership process.
New York City, under new Mayor Zohran Mamdani, hopes to intervene in the bankruptcy to delay the sale. He visited a Pinnacle-owned building in Brooklyn on Jan. 1, his first day in office.
His office said in a press release that the city plans to “take action to seek immediate relief and improve living conditions for Pinnacle tenants, an unprecedented step on behalf of renters living in some of the city’s most neglected buildings.”
Most of the units, located in Manhattan, Brooklyn, the Bronx and Queens, are rent-stabilized.
In May, they were put into Chapter 11 bankruptcy when Flagstar, which holds $564M of mortgage debt tied to the apartments, moved to foreclose on them and wanted to appoint a receiver to oversee them.
More than $1.1B tied to the portfolio is owed to Flagstar and Israeli bondholders from companies owned by Pinnacle Group CEO Joel Wiener. These companies also owe millions to facilities providers, contractors and vendors.
The cost to cover the debt service on the portfolio skyrocketed by 75% in two years, Wiener said in a court filing. He also said the rise in interest rates is to blame for the payments going from $36M in 2023 to $45M in 2025. Pinnacle became unable to cover the jump in mortgage payments after other expenses were taken care of.
Pinnacle used building management fees and condo conversions to pay the mortgage, but the company was unable to raise rent to cover payments due to the units' stabilized status. The 2019 Housing Stability and Tenant Protection Act placed restrictions on how much of the repair costs could be passed on to tenants and which units could be removed from stabilization.
Wiener and Flagstar met to discuss a lower debt payment in 2024, but they never came to an agreement. Pinnacle stopped paying interest, and Flagstar moved to foreclose on the units in March.
UPDATE, JAN. 4, 9:20 P.M. ET: This story has been updated to include planned action by New York City Mayor Zohran Mamdani to intervene in the bankruptcy sale.