New York City REIT is at risk of defaulting on loans for four commercial buildings that make up half of its portfolio, the landlord disclosed in its latest quarterly report.
The REIT has breached covenants on loans for four of its New York City properties over the past year, with its debt on the assets totaling over $200M. It attributed the woes to early lease expirations and tenants experiencing “financial difficulties," The Real Deal reported.
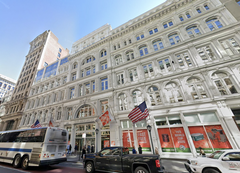
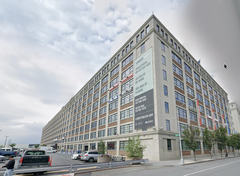
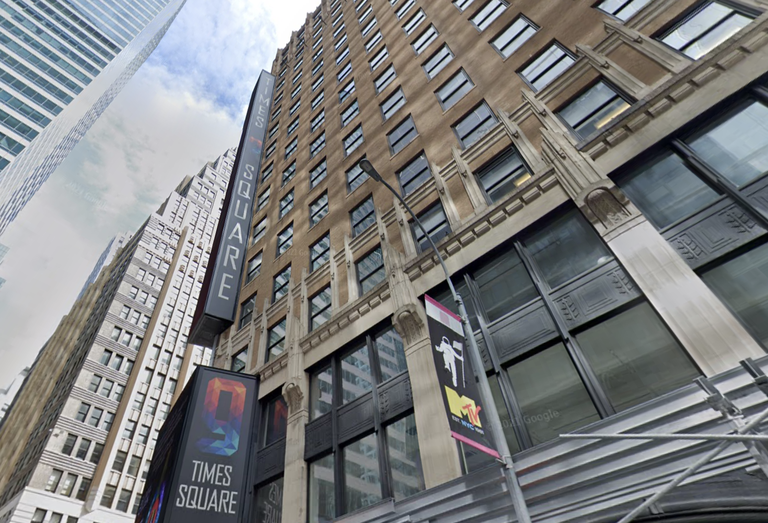
The four properties where NYC REIT has faced these issues are: 8713 Fifth Ave., 1140 Sixth Ave., 9 Times Square and 400 East 67th St./200 Riverside Blvd.
Together, the buildings account for 550K SF, roughly half of the REIT’s eight-property, 1.2M SF portfolio. The portfolio, consisting of office and retail buildings, was valued at roughly $854M as of last quarter, according to an investor filing.
The company is not automatically in default because of these breaches, but it reportedly failed to set aside the money needed to cover its debt service. It has managed to get back into compliance for 400 East 67th St./200 Riverside Blvd. and has paid down a portion of its principal loan for 9 Times Square.
New York City REIT CEO Michael Weil warned in a Securities and Exchange Commission filing that it expected to be in breach on some of the loans in the near future — a pattern that could land the REIT in default if it persists, The Real Deal reports.
A representative for NYC REIT told The Real Deal that it hasn't defaulted on any loans. But the difficulties come at an already-troubled moment for the REIT, which is facing a heated campaign over a board position from an activist investor.
The REIT has been in the middle of a proxy battle since December, with Comrit Investments 1 LP complaining of declining stock prices and nominating an independent member for a seat on the REIT’s board.
Comrit alleged late last year that CEO Michael Weil and the REIT’s board are allowing the stock price to depreciate, noting a 60% decline in price over 15 months.