Blackstone is getting closer to an extension on a $195M loan on the former Charles Schwab headquarters in downtown San Francisco.
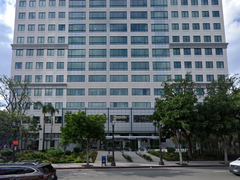
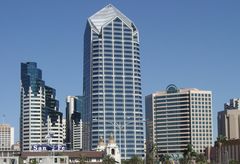
The New York-based investment firm wants to extend the loan that matured earlier this month for 211 Main St., a 415K SF office building that was once fully occupied by Charles Schwab Corp. The property entered special servicing in February, CoStar reported.
“This is a procedural step needed to effectuate a change to the term of the loan, which requires approval from the special servicer,” a Blackstone spokesperson told Bisnow via email.
Following a modification to a loan term, all properties must remain in special servicing for a minimum of three months.
“This building is 100% leased to a high-quality, credit-worthy tenant through 2028,” the spokesperson wrote.
Schwab, which occupied all 17 floors of the building until 2019 when it relocated its headquarters to Dallas in a controversial move, now leases 170K SF at the property. The downsizing came after the company’s latest round of layoffs in November when 2,000 people lost their jobs.
SFGate reported that Schwab cut 5% to 6% of its workforce at that time to reduce operating costs. The company aimed to save at least $500M annually by shedding part of its workforce and slashing its real estate footprint nationwide.
Blackstone has been busy in the Bay Area lately. In January, Blackstone and Paramount Group extended a $925M financing package collateralized by One Market Plaza, a 1.6M SF office in San Francisco occupied by Visa, Google and others.
Blackstone also nabbed a $422M CMBS loan that month for a large life sciences campus on the peninsula in a $1.2B transaction that included three Boston assets.
It hasn't all been good news, though. Blackstone defaulted on a $245M mortgage for its Club Quarters Hotel downtown and handed the 346-key property over to its lender.
Last year, San Francisco had the third-most outstanding office distress in the U.S., totaling $2.2B. Manhattan led the nation with $9.6B of distressed office properties in 2023, and Los Angeles came in second with $2.3B, MSCI Real Assets reported.
CORRECTION, APRIL 18, 8:17 P.M. ET: This story has been updated to correctly reflect distressed loan totals associated with office properties in San Francisco, Manhattan and Los Angeles.