U.S. industrial absorption is on track to finish 2018 with its third-strongest net occupancy growth this cycle, behind only 2016 and 2014, according to Cushman & Wakefield's Q3 2018 report on the industrial market. That finding agrees with other recent assessments of the market.

Moreover, the outlook is bright for more occupancy growth across all classes of industrial product. The combination of limited new product and high utilization rates for existing footprints will mean strong performance for Class-A product, but also improved performance for Class-B and C product.
Will such strong leasing inspire a glut of new development? For now at least, development has ticked upward, the report reveals. Construction starts jumped by 22.4% year-over-year nationally during Q3 2018, with 34 markets experiencing an increase in construction starts during the quarter. Regionally, the largest increase was in the Midwest, where the development pipeline increased 34.5% since the second quarter, Cushman & Wakefield reports.
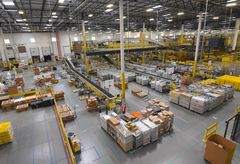
The strength of the market comes at a time when changes in logistics and distribution are fundamentally reshaping parts of the U.S. industrial market. For instance, e-commerce has been stimulating leasing and development during recent years, and as online sales continue to rise, that trend will likely continue.
Also, multistory warehouses — unheard of only a few years ago — are becoming more common in densely populated metropolitan areas due to the high land prices, dense populations and the high concentration of e-commerce shoppers in these markets.
Even wild-card factors such as the worsening trade dispute between the United States and China don't seem to be affecting the domestic industrial market, at least not yet.
All together, U.S. industrial markets absorbed 66.3M SF in the third quarter, pushing year-to-date absorption to 203.9M SF, a 10.5% increase from the 184.5M SF absorbed during the same period last year, Cushman & Wakefield reports.
Leasing demand continued to be broad-based, with 41 markets enjoying over 1M SF of net absorption so far this year, and 29 markets seeing 2M SF of gains year-to-date.
Annual net absorption for warehouse/distribution space surpassed 180M SF, while manufacturing and flex space absorption nearly doubled during Q3 2018, with those segments absorbing 13.6M SF and 6.4M SF, respectively.
Gateway markets aren't the only ones experiencing strong activity. Strengthening fundamentals in secondary markets have helped spur solid occupancy growth, with over 30 secondary markets registering more than 1M SF of net absorption year-to-date, the report says.
Average annual rent growth for both warehouse and manufacturing are forecast to be strongest in secondary markets in 2018, although growth will also be strong in primary and tertiary markets.