Nightingale Properties, fending off foreclosure and scandal up and down the East Coast, is reportedly in default at yet another property in Manhattan.
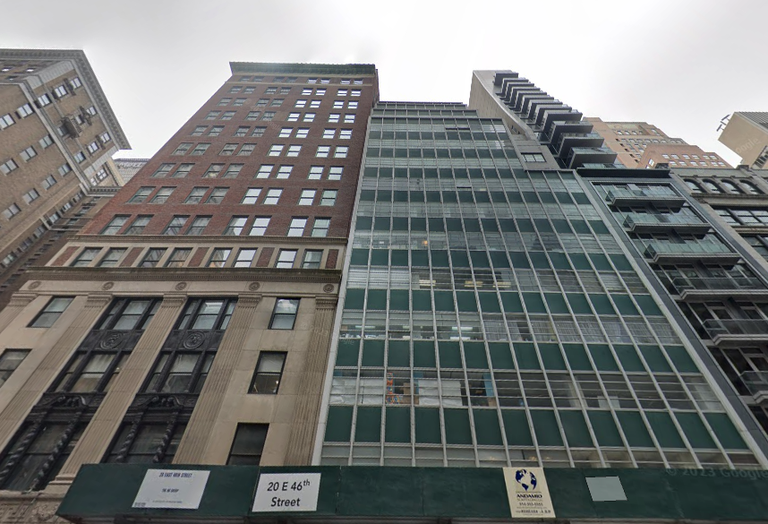
The company, which is under federal investigation for allegedly embezzling funds it raised in two failed crowdfunding deals, defaulted on the $30M loan it held on 20 East 46th St., The Real Deal reports.
The company, run by CEO Elie Schwartz, stopped meeting its obligations earlier this year, prompting East West Bank to sell the debt to Klosed Properties and the Namdar Group, TRD reported. Nightingale landed the $30M in 2016 when it paid $28M for the leasehold on the property from Gary Barnett.
The lease had 27 years left and the balance of the loan at the time of default was $26.2M, per TRD. Rosewood’s Ben Khakshoor helped arrange the debt sale.
Nightingale's portfolio — which once spanned 22M SF across $10B of investments, according to its website — is increasingly under pressure as the company has struggled with its debt.
The company, with its partner, InterVest Capital Partners, is also facing foreclosure at 111 Wall St. after the mezzanine lender on a $500M debt package initiated an auction that is set for next month. Nightingale's 1500 Market St. in Philadelphia — the biggest office property in the city — has been in receivership since April after the lender on that building filed to foreclose on it.
Schwartz's firm is also facing foreclosure at a 420K SF Sunset Park commercial building it acquired in 2020. Its lender at 300 Lafayette St., an office and retail property in SoHo, moved to foreclose on the building this summer, but InterVest, also a partner there, bought the defaulted note and canceled the action, Crain's New York Business reported.
Those financial troubles have come as Nightingale faces apparent legal peril regarding equity it raised on the real estate crowdfunding platform CrowdStreet. The firm had raised $63M to acquire a huge office complex in Atlanta and renovate an office building in Miami Beach, but it never closed on the deals.
An independent manager appointed to oversee those entities after Nightingale stopped responding to investors accused Schwartz of misappropriating the funds, draining the accounts and diverting roughly $40M to accounts he controlled. CrowdStreet has come under fire as a result, culminating in the ouster of its CEO last month.