Mergers and acquisitions, across industries, have an impact on your business. Commercial real estate and M&A have an under-the-radar parallel based on similarities in motivation, valuation and financing deals. And of course there's a connection between the purchase of companies and the purchase of buildings, so tracking the sector can provide a forward-looking indicator for the commercial real estate industry.
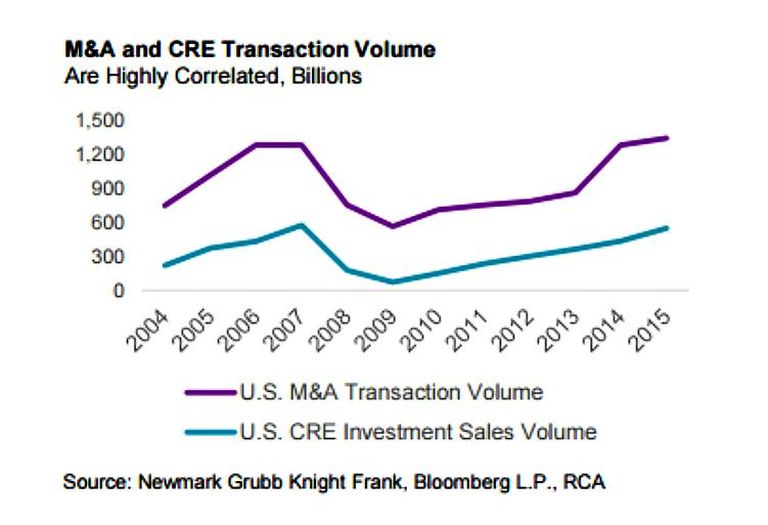
Since CRE and M&A activity are both impacted by the availability of capital, the cost of capital, risk and sentiment, NGKF director of research David Wegman tells us their valuation metrics move in tandem.
Both use discounted cash flows. Sales comparables in CRE and comparable company analysis in M&A also share similarities. Direct cap rate/income approach in commercial real estate mirrors a comparable transaction analysis in M&A. Lastly, replacement cost in commercial real estate is the equivalent of Tobin's Q ratio in M&A.
Optimism or pessimism in one space carries over into the other. And the similarities play out in the numbers, as shown by this graph tracking the volume of both M&A and CRE investment sales.
Companies join forces for a multitude of reasons, but David says the primary drivers for M&A activity across sectors are synergies, increased market share, growth and diversification.
These factors are similar to those for acquiring or disposing of assets in a real estate portfolio.
But these similarities play out at different points in the economic cycle—M&A activity is a forward-looking indicator for the US commercial real estate market, thanks to key macro factors. From 2004 to 2015, the unemployment rate, real GDP growth and the leading economic index (LEI) seemed to influence M&A transaction volume the most. Meanwhile, interest rates, which certainly influence valuation, have been less impactful to overall volume.
Despite signs that we are nearing a market top, including slower M&A activity in 2016, the macro environment offers hope.
By factoring in the historical lag time associated with GDP growth, this would suggest a stable outlook for CRE and M&A transaction volume through 2018. Adding to the optimism, the US unemployment rate is expected to remain low through 2018, and the LEI is higher in June 2016 than at year-end 2015. All told, while cautious optimism is warranted, the macro environment and acceptance of real estate as an asset class point to ample liquidity for commercial real estate during 2017 and 2018.