Simon Property Group took out a $93M loan for Lakewood’s Colorado Mills mall, with $80M being sold into CMBS, according to a term sheet filed with the Securities and Exchange Commission on Monday.
The loan, granted by Goldman Sachs and German American Capital Corp., has an interest rate of approximately 6.84%. It is set to mature in November 2036, according to the SEC filing.
Simon didn’t respond to multiple requests for comment from Bisnow.
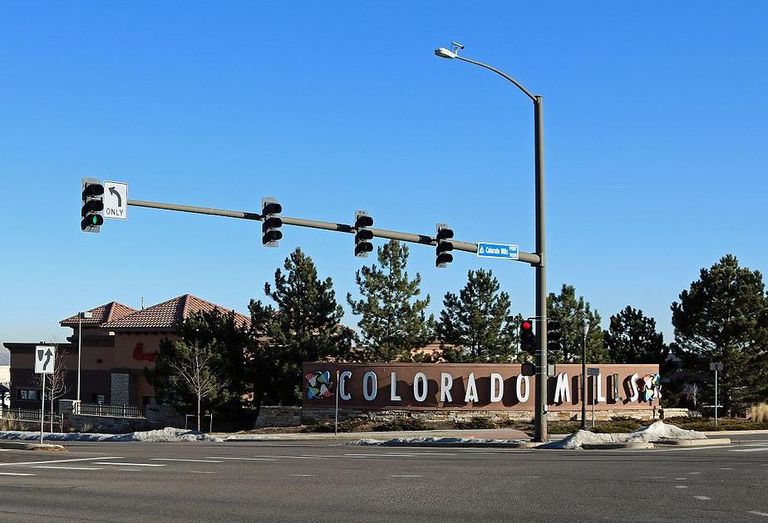
Colorado Mills is one of the largest shopping centers in the Denver metro. The 1.4M SF mall was built in 2002 and renovated after a ferocious 2017 hailstorm that seriously damaged the property and led to its temporary closure. It was 98% occupied as of Aug. 31, according to the SEC filing. The mall added Cavender’s Boot City as a new tenant earlier this month.
In early 2025, Colorado Mills was reappraised at $135M, 37% less than its 2014 valuation.
Simon took out a $117.7M loan in 2014 that was transferred to special servicing before its November 2024 maturity date, Bisnow previously reported. In May 2025, after the property was reappraised, Simon avoided default on the loan by securing a two-year extension deal.
Colorado Mills’ net operating income has fluctuated over the years, but the property appears to be performing better this year. Its net operating income through the first seven months of 2026 was about $18.7M, up nearly $1.3M from last year, according to the SEC filing.
Colorado Mills’ $80M CMBS loan is part of an $805M pool with 63 commercial mortgage loans backed by 79 properties across the U.S. The local mall’s loan is the largest in the pool, accounting for about 10%, Kroll Bond Rating Agency said in a statement.
Malls across the country have faced shifting market conditions over the past decade. The number of malls in the U.S. dropped from 2,500 in the 1980s to 700 in 2024. Despite the closures, malls are now the “top performer in commercial real estate,” with values increasing 13% year-over-year, The Wall Street Journal reported.
Park Meadows mall in Lone Tree also faced a potential default in 2024. The mall’s owner, Brookfield Properties, refinanced by securing a $700M loan with a five-year term just days before its previous $615M property loan matured.