Brookfield is one of the world’s largest commercial real estate investment firms, with $280B in assets under management. It oversees nearly 550M SF of real estate across a diverse portfolio, including office, multifamily, hospitality and industrial assets.
But when CEO Lowell Baron joined the firm in 2005, Brookfield looked drastically different.
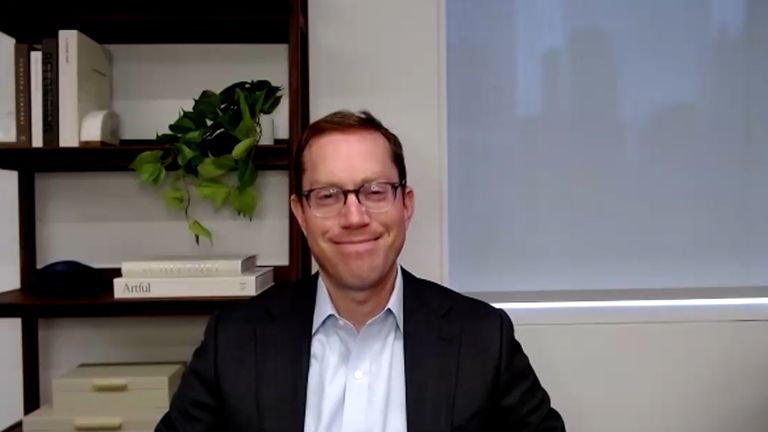
After a nine-year tenure at Deutsche Bank, Baron joined the firm when it was much smaller — servicing just one $600M real estate credit fund and in the beginning stages of building out its investment strategy.
“Part of the reason I left Deutsche Bank was I felt it was hard to work in a place that was so large and had so much process and planning to it,” Baron said on this week’s Walker Webcast, hosted by Walker & Dunlop CEO Willy Walker. “I would sit there and work on successive credit memos and investment committees, and there was a whole process to get things done. I wanted to be in a place where we could actually build something and grow it with real efficiency.”
Fast-forward to today. Brookfield is one of the industry’s “behemoths,” Walker said, and there are two main tenets the company uses to guide its business: investing its own money and operating its own properties.
Baron said Brookfield was always an investor first, as opposed to many of its competitors that grew up as investment managers, scrambling to bring money together and investing on behalf of their clients. Brookfield was fortunate enough, Baron said, to be a public company with a large balance sheet, so it invested its own money first.
It also had a 50% ownership interest in a public company that owned office buildings, meaning it already had experienced teams that knew how to lease and manage office buildings. This gave Brookfield the confidence to bring its expertise to other asset classes over the past 20-plus years, he said.
“We successfully reached each sector across the globe that we wanted to be in by either building or buying an operating platform in that sector,” Baron said. “It’s a unique setup, and it's almost irreplaceable, because unless you’re starting with a large balance sheet of assets, you can't afford to create all these operating platforms. We don't really see anyone else being able to replicate our capabilities.”
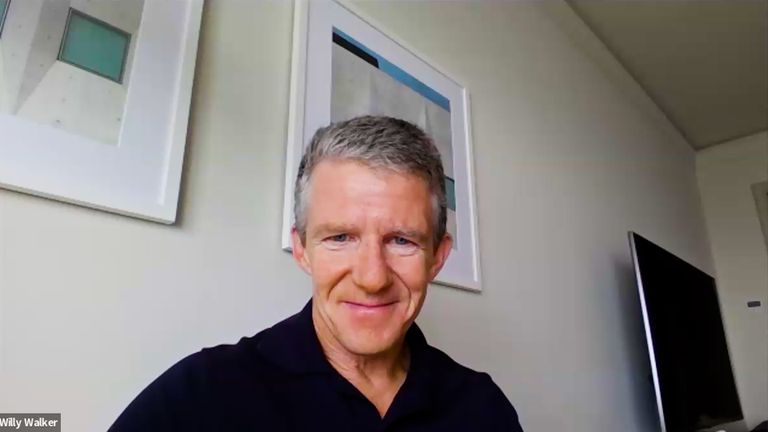
Walker pointed out that the strength of Brookfield’s real estate strategy has been evident in recent months, when it’s been able to raise a $16B fund from institutional investors and another $2B from private investors — despite a turbulent economy that has shaken others.
Baron said that while many have been sitting on the sidelines trying to weather the storm, Brookfield has been very active over the past two years. He believes that today’s commercial real estate market presents a great opportunity for buyers looking to make moves.
“From a buying perspective, we think we're at the early days of recovery,” he said. “We think we're two years into that recovery, and there's a lot of headlines and volatility that are masking it. People aren't really paying attention to what's happening on the ground. But part of it is the reality of real estate, which is that it is a relatively slow-moving industry, and it's often backwards-looking.”
He added that some investors delay selling their properties in hopes of cap rates improving in the near future. This is a “very bad strategy” that can get investors into a troublesome holding pattern.
In periods of economic uncertainty, Baron said Brookfield gets creative with how it sells assets. People want to get into a sector that's attractive, he said, and even if in today's market they are a little nervous about real estate, they’re likely to see through it.
“What we do is build up these operating platforms, even inside our investment vehicles,” he said. “Inside our funds, we may build up a student housing business in Europe or a self-storage business in Australia, and … when we go to sell those, they're actually very attractive to the market and to large pools of capital because they're so unique.”
One sector that has seen activity cool down is multifamily, Walker said, hinting that after speaking with other housing executives, new construction starts in 2027 could fall at or below 250,000 units. But one silver lining for existing multifamily stock is that fewer apartments being built in the near term signifies potentially stronger returns and rent growth in the long term.
And while many investors may not be optimistic about the housing sector at the moment, Brookfield is “pretty excited” for what’s to come, Baron said.
“One of the things we love about housing is being able to invest across all these different age cohorts and demand generators,” he said. “We’re investing in student housing, different types of multifamily, single-family homes, manufactured housing and senior living … The ability to get the right strategy of mixing those subsectors lets you reduce risk and increase returns. It's pretty amazing.”
Brookfield’s portfolio also contains data centers, and a good chunk of the firm’s assets is open land, which could play well in the booming data center market. Industrial land has been a sector that Brookfield has taken an interest in the past five years, taking into account that these land sites have the ability to get excess power.
“We started applying for excess power to many of our sites, thinking there's no downside, and if we could get power, there could be interesting data center opportunities,” Baron said. “We have these data center sites littered across our portfolio that either we can build out ourselves, or we can sell them as powered land to someone else.”
Baron said there’s no doubt in his mind that data centers will continue to be a strong market, even if building out the infrastructure may take some time. The demand for artificial intelligence is not going to slow down anytime soon.
“Clearly, there's a lot of pushback, and I think the result of that probably is that the build-out just happens slower,” he said. “In some ways, maybe it’s healthier. It may not be such a bad thing if it happens slower, but it’s going to happen.”
Subscribe to the Walker Webcast on YouTube for new episodes every week.
This article was produced in collaboration between Walker & Dunlop and Studio B. Bisnow news staff was not involved in the production of this content.
Studio B is Bisnow’s in-house content and design studio. To learn more about how Studio B can help your team, reach out to studio@bisnow.com.