Florida's new, privately run train, Brightline, has already sold $600M in private activity bonds and started up luxury service between Miami, Fort Lauderdale and West Palm Beach. To extend to Orlando as planned, it is seeking another $1.75B in bonds, and Wednesday will ask the Florida Development Finance Corp. to issue them.
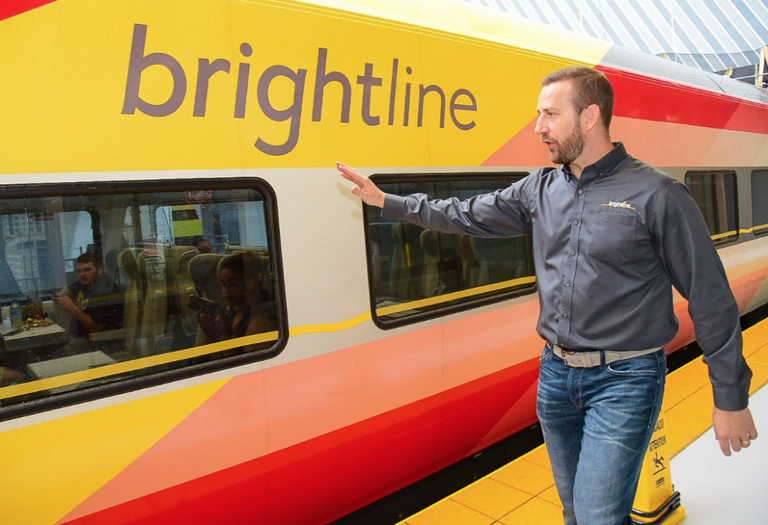
The request from Brightline's parent company, All Aboard Florida, will be heard by three board members, as two positions on the board are vacant, according to the Bond Buyer. A vote is expected.
In a packet of materials made available for Wednesday's meeting, a consultant wrote that the bonds would be sold as non-investment grade or unrated and that projected cash flow from operations and debt service coverage was "TBD." However, he pointed out that last year's bond offering "was oversubscribed by 3.77X after receiving institutional QIB [Qualified Institutional Buyers] orders from 61 investors totaling over $2.26B" and recommended the new bonds be issued with some caveats.
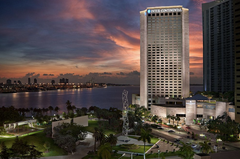
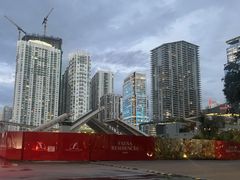
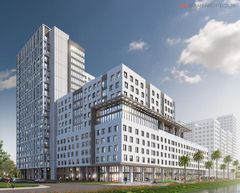
Brightline operates 32 trains per day. It plans to extend to Orlando by 2021. The trains have helped trigger investments in real estate around brand-new train stations. The MiamiCentral development, which encompasses a train station, takes up 1.6M SF with two new office towers, new apartment towers and retail. Investment has likewise boomed around stations in Fort Lauderdale and West Palm Beach.
In the packet for the meeting, All Aboard Florida noted that FECI, its parent company, had invested $1B in real estate projects around its stations and "could generate net proceeds from the sale of these developments of approximately $1.4 to 1.5B," though any such proceeds would not be collateral for the bonds.
The Brightline project has faced legal challenges by two counties north of Palm Beach, where the trains would pass through, but not stop, on their way to Orlando. This week, Brightline revealed that it is exploring the feasibility of adding a stop or stops there.
Some critics have doubted the train's ability to turn a profit, but the company contends that it will take a few years to stabilize ridership, and is even powering ahead with plans to extend to Tampa. This week, Tampa municipal leaders and potential investors traveled to South Florida to ride the trains and meet with company execs.
Florida Gov. Rick Scott in 2011 rejected federal funding for high-speed rail, saying that state taxpayers would get stuck with additional costs. His financial ties to Brightline have since been scrutinized. The Florida Bulldog reports that he holds a previously undisclosed stake in a Chinese company supplying the maker of Brightline trains.