The national office market may be stabilizing, but its full recovery likely won't be in time to save a subset of office buildings from financial distress next year.
Over $7B of loans backed by office buildings and packaged into commercial mortgage-backed securities is coming due in the next 12 months, and many of the buildings involved have significant vacancies opening up over the same time period, making refinancing unlikely, Bloomberg reports. Underwriters will likely take a conservative approach to any building with vacancy that reduces the ratio of cash flow to loan amount.
The reasoning behind underwriters' conservatism is that until true leasing momentum builds up, they are most likely to use 2020 cash flow data, making refinancing less likely and loan sizes likely to be smaller, according to commentary by Moody's Analytics reported by Bloomberg. The risk is more elevated for office properties in areas where occupancy was hit hardest by the coronavirus pandemic and recovered the least, which is more likely to apply to urban cores in gateway markets.
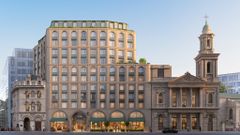
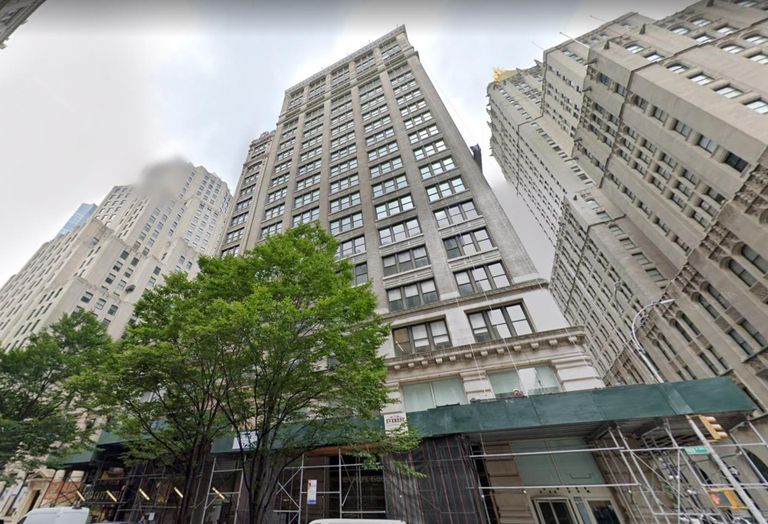
One such property unlikely to be refinanced is New York's 360 Park Ave. South, which is staring down expiring leases for 100% of its square footage in December while a $201.5M loan securitized in 2007 is scheduled to mature, Bloomberg reports. The 462K SF building is under contract to be sold by Enterprise Asset Management to Boston Properties, which is already marketing the building based on planned renovations to the interior.
Eight buildings analyzed by Moody's, including 360 Park Ave. South, have at least one lease due to expire in the next year and maturing loans tied to CMBS packages with low debt yields, Bloomberg reports. A further 17 buildings have at least 20% of their square footage facing potential vacancies in the next three years, pending tenant renewals.
The renewal question will be central to whether the office loans being tracked by Moody's for distress can be refinanced. If they can't, the recent track record for borrowers meeting their maturing debt obligations is less than sterling: Only 35% of loans that matured last year were paid on time, representing 65% of the CMBS debt that came due last year, Bloomberg reports.