A large chunk of investor Moshe Silber’s real estate portfolio is going up for auction while he serves a 30-month prison sentence on fraud-related charges.

A creditor with control of roughly 6,300 multifamily units once associated with Silber is planning to auction the portfolio on Thursday from the Rockland County Sheriff’s Office in New York, The Real Deal reported. Silber is serving a prison term for his role securing a fraudulent loan from Fannie Mae.
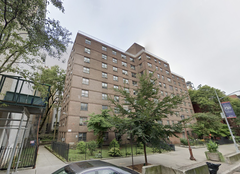
The auction is for CBRM Realty, a holding company for four other entities associated with Silber, according to TRD. The apartment properties include two in Flint, Michigan; two in Baton Rouge, Louisiana; one in Jackson, Mississippi; and 1,305 units in the portfolio of Pittsburgh’s Allegheny Housing Rehabilitation Corp. A suburban office complex in northern New Jersey is also part of the portfolio.
One of Silber’s creditors sued after he defaulted on $20M worth of loans in March 2024, five months before he pleaded guilty to his role in the $119M fraud scheme. The lender, Denver-based Acquiom Agency Services, won the case and assigned the rights of that judgment to Spano Investor, which in turn asked a court to force the auction, according to TRD.
Silber is also being personally sued by Spano over the unpaid loans in a separate case, court records indicate.
Bernard D’Orazio, an attorney for Spano Investor, told TRD in a statement that he expected the sale would generate substantial interest and be executed without opposition from Silber or any other party.
Silber pleaded guilty in August to falsifying financial records to secure Fannie Mae financing for a project in Cincinnati. Silber, Frederick Schulman and Chaim Puretz used a stolen identity and fake purchase and sale contract to secure the agency debt from JLL to buy the property in 2019.
JLL ultimately lost $18M buying back the loan last year after investigators uncovered that the three investors inflated the price they paid for the apartment complex, called Williamsburg of Cincinnati. The investors purchased the 976-unit development for $70M, told JLL and Fannie Mae they paid $96M, and secured a $74M loan for the deal.
As the new owner, JLL is looking to stabilize the asset before selling it, JLL Chief Financial Officer Karen Brennan said on the brokerage firm’s second-quarter earnings call in August.
The fraud scheme was uncovered as Fannie Mae, Freddie Mac and their regulator, the Federal Housing Finance Agency, embarked on a public push to root out fraud that began during Joe Biden’s presidency and has continued under President Donald Trump.
New rules were put in place in August to provide more visibility and oversight into loan underwriting standards for agency debt, almost a year after Fannie Mae updated its rules and increased its scrutiny of broker-involved loans.