As urban core office markets reckon with a historic amount of maturing debt this year, a picture is emerging of the hefty price tag for kicking the can down the road.
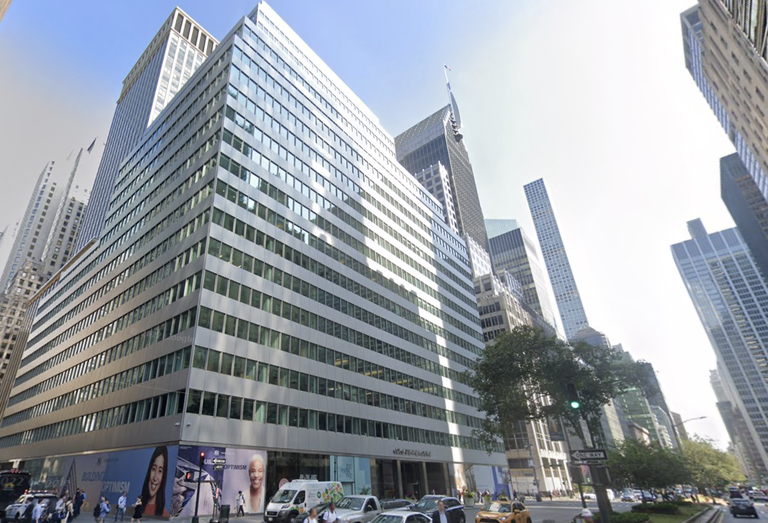
When RFR Realty reached an extension in May with holders of the $783M mortgage for 300 Park Ave. in Midtown Manhattan, also known as the Seagram Building, it paid down $15M of the principal, covered all special servicing and lender expenses, and agreed to pay off a further $40M over the next two years, according to commentary by the loan's special servicer Midland Loan Services reported by Morningstar Credit.
As part of an extension early this month for a $485M loan backed by 300 Park Ave., Tishman Speyer paid $30M into a reserve fund for leasing costs, The Real Deal reports. Like RFR, Tishman's extension is for one year with an option to extend for a second.
GFP Real Estate agreed to pay down $5M of the $120M loan backed by 515 Madison Ave., also known as the DuMont Building, just a few blocks north of the Park Avenue buildings, TRD reports. GFP also agreed to sink millions into reserve funds for tenant improvements and leasing commissions in case it can land a tenant.
All three loans were single-asset, single-borrower, commercial mortgage-backed securities, and the deals were reached after the loans were sent to special servicing.
With office values dropping precipitously across New York and nationwide, lenders are motivated to keep buildings in the hands of borrowers as long as possible in the hopes that conditions improve in a couple of years.
Office sales happening this year are more likely than not a result of landlords cutting bait and receiving much less than the price they had initially paid. Others have simply ceased payments on their loans, letting the chips fall where they may.
Without a borrower willing find a buyer or sink more equity into their properties, lenders have little choice but to preserve whatever value they can with foreclosure or deed-in-lieu transactions, the latter of which are favored by private equity giants eager and able to cut loose money-losing properties.