Two office properties in Denver’s River North Art District have run into financial trouble in quick succession. It is the latest sign that Denver’s once-buzzy creative corridor is facing mounting challenges in a shifting commercial real estate landscape.
The owners of The Hub North at 3660 Blake St. surrendered the property to their lender last month via a deed-in-lieu-of-foreclosure transaction. The building holds 102K SF of office and 8,500 SF of ground-floor retail.
Public records show Eagle Point Capital and Farallon Capital Management paid $40.5M for the eight-story building in 2021 and financed it with a $37.3M loan from Ares Commercial Real Estate Management.
That loan matured last fall. Ares took over the building last month for $30M.
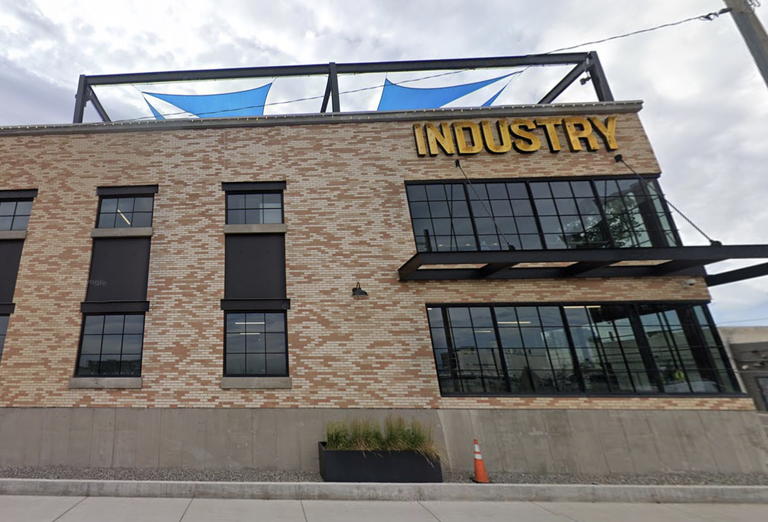
Just a few blocks up, Industry RiNo Station, a 150K SF office building at 3827 Lafayette St. that was developed in 2017, has stopped making payments on its $60M loan, according to a loan report provided to Bisnow by Trepp.
The building is 75% leased, according to Trepp, but most of its tenants have leases that expire before September 2026.
Industry leaders didn't respond to requests for comment.
The twin defaults deepen a trend of distress across RiNo’s office market, where at least four buildings have changed hands under financial strain in the past year. Zeppelin Station was placed in receivership last year, and the original Industry Denver building sold at a loss a few months later. Rev360 at 3600 Brighton Blvd. traded hands in January for 53% less than its 2021 sale price.
RiNo’s challenges are compounded by its heavy pipeline of mixed-use development. A recent Bisnow analysis found that retail vacancies are rising in the district.
And the news comes as office rentals struggle across Denver’s urban core.
Twenty-three percent of the city’s CMBS property loans are delinquent, according to a recent Trepp report provided to Bisnow. Forty-seven percent of all CMBS-backed buildings have a vacancy rate above 25%.
The city’s overall office availability rate, which includes sublease space, was about 30% in the fourth quarter, according to Savills data. Downtown Denver had the highest availability, at 40.8%, while the RiNo and Lower Downtown submarkets had a combined rate of 34.5%. All of those areas had increasing rents in the $45-per-SF range.
Those factors are, at least in part, driving the citywide trend of owners walking away from their properties. Urban Renaissance Group gave up ownership of 2399 Blake St. and its parking lot at 1561 Park Ave. in January.
In July 2024, RRA Capital took control of Novel Coworking’s 124K SF 1630 Welton St. building to prevent foreclosure. The following November, Rising Realty Partners gave up ownership of Civic Center Plaza, a 599K SF office tower at 1560 Broadway. A lender foreclosed on Novel Coworking’s Trinity Place at 1801 Broadway in December.