Dallas-Fort Worth’s office market rebounded in the third quarter after a slow second quarter, showing strong positive demand with 1.1M SF of net absorption. While activity is strong, vacancy continues to rise due to deliveries exceeding net absorption, according to JLL.
Steady job growth of over 3% annually has been driven primarily by expansions as headliner corporate relocations slow.
With low unemployment, the tough competition for top talent can be seen in the widening gap between Class-A and Class-B activity. Class-A absorption for Q3 stood at 855K SF, but Class-B was less than half that at 308,521 SF, according to JLL’s Q3 2018 Office Insight report.
The Far North Dallas submarket led all submarkets in absorption with over 500K SF of net absorption.
In Fort Worth, XTO’s move to Houston pushed absorption negative for the quarter and year, bumping vacancy up 40 basis points.
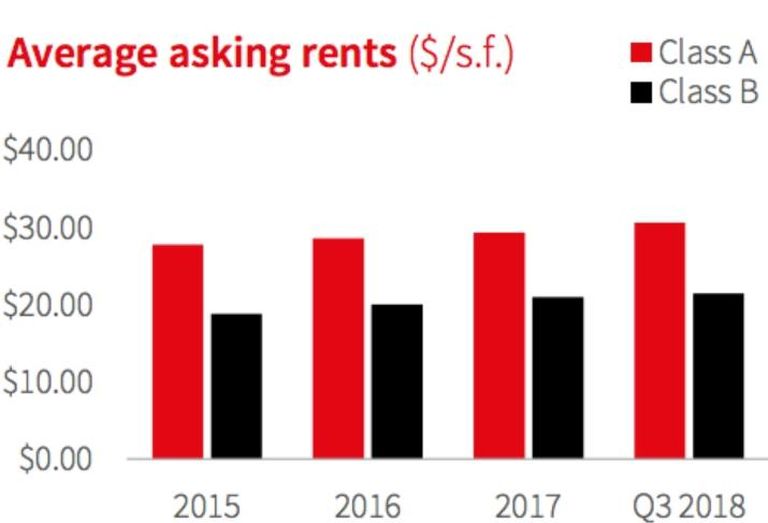
Rental rate growth confirms the strength of Class-A in Dallas-Fort Worth. Rents grew 5.9% from Q4 2017 to Q3 2018 in that asset class, while Class-B rates grew just 2.3% over the same time period. Asking rents grew the most in Class-A properties in Preston Center and Uptown, spurred by rising taxes and operating expenses.
With annual rent growth topping 5%, JLL said the DFW region will continue to be a landlord market, and tenants will continue to right-size space as leases roll.
Here’s a quick look at key Dallas-Fort Worth statistics in the office market:
1. Year-to-date net absorption: 2.1M SF
2. Under construction: 6.2M SF
3. Total vacancy: 19.7%
4. Average asking rent: $27.68/SF
5. Concessions: Stable
Here are four things to keep an eye on nationally:
1. Coworking is becoming a leader in leasing with more than 12.8M SF in transactions in 2018, third behind technology (16.1M SF) and finance/insurance (14.3M SF).
2. Occupancy growth remains muted. Absorption is on track to be 29% lower than 2017.
3. Class-A product continues to outperform as the flight to quality continues, causing the net absorption between Class-A and Class-B properties to widen.
4. Office building rents are on the rise in many places with Oakland-Eastbay, Seattle-Bellevue and Fort Lauderdale seeing the biggest increases.