The commercial real estate market is facing mounting financial pressure, but property owners aren’t budging.
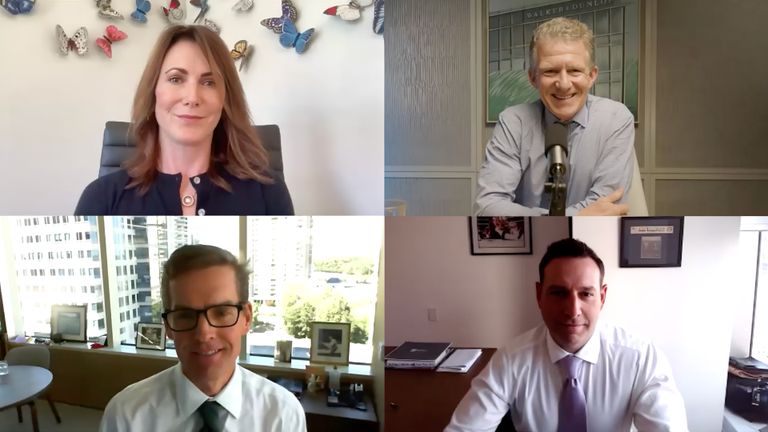
Kris Mikkelsen, executive vice president and co-head of capital markets at Walker & Dunlop, said owners are holding on to their assets tightly. But for most of the sales that do occur, the No. 1 motivation for sellers is that business plans have naturally run their course, he said on this week’s Walker Webcast, hosted by Walker & Dunlop CEO Willy Walker.
Financial distress hasn’t translated into forced sales, yet, Mikkelsen said.
“Some of the pressure that is building with [interest] rates and margin requirements is going to be a forcing mechanism for transactions that probably needed to occur over the last couple of years,” he said. “But because the credit markets are as liquid as they are, there's been a lot of impaired equity that's been able to hide because of a hyperliquid credit environment.”
Aaron Appel, senior managing director, capital markets, and co-head of institutional advisory at Walker & Dunlop, agreed that a shortage of capital isn’t the main reason for today’s uncertain financial markets. Rising interest rates and shifting asset values are making it more difficult to get deals across the finish line.
“We still see a tremendous amount of credit available across the board,” he said. “I think the bigger issue is how people are valuing real estate. The last real thrust above a 5% Treasury has affected valuations that lenders are looking at, and also buyers.”
He added that lender cap rate margins recently widened by 25 to 50 basis points for multifamily and industrial assets. Office and hospitality assets aren’t witnessing the same adjustment, Appel said, because they were already being valued more conservatively.
“To put this in perspective, we have about 50 transactions in the pipeline to close by year-end, and we’ve seen seven or eight in the past week not close right away,” he said. “There were minor issues that normally would’ve been nonissues, but we’re seeing lenders now behaving in a fickle manner.”
Narrowing in on the housing sector, Ivy Zelman, executive vice president and co-founder of Zelman, a Walker & Dunlop company, said that over the past six weeks, there’s been a “definite step down” in the levels of activity — which was already in a fairly weak state to begin with.
While single-family inventory is rising, home prices are going to fall further, she said. Many homebuilders that had previously been prudent with interest rate buy-downs, which negatively impacted their margins, now can’t afford to keep buying them down as low as people need to qualify — so the market has gotten “too expensive.”
Even the luxury buying cohort has witnessed some restraint recently, as geopolitical tensions rise and consumer confidence has weakened, she said.
“There's really nothing positive,” Zelman said.
On the rental side of the housing market, Zelman added that while there’s still excess supply, it’s showing signs of improvement.
“I feel pretty confident, given the strength we see demographically for rental households growing, that we're going to absorb that supply, and we're going to continue to see low turnover,” she said. “Lease-up competition is still very elevated, but multifamily, relative to for-sale, is going to be a better-performing sector.”
Walker pointed out that over the past three years, rent growth fared well for the first six to seven months of the year, then tailed off to be either flat or negative the remainder of the year. As of September, rent growth is holding steady and hasn’t trailed off as it did previously.
This is a good sign, Appel said, but the story of rent growth can’t be painted with a broad brush — every market in every region has its own nuances.
For instance, he said, areas that have been heavily regulated and that repelled capital for a long time, such as San Francisco, now may have significant amounts of economic growth. Primarily driven by an artificial intelligence boom, exponential rent growth can be seen throughout the Bay Area. In New York City, rent growth has been very resilient, he said, but for markets in the Midwest and Sun Belt, it’s a different story.
“You see slow and steady growth in the Midwest, but in the Sun Belt markets, you still see pressure on rates,” he said. “Interestingly enough, some of the deepest bid sheets that we have are in those overbuilt Sun Belt markets, where the basis has gotten so low relative to replacement cost that it's attracting a lot of capital.”
As for the data center sector, the magnitude of investment that’s pouring in cannot be ignored, Walker said. But is AI experiencing a bubble that’s going to burst?
Mikkelsen pointed out that Anthropic’s revenue has gone from an annualized basis of $9B per year at the start of 2026 to $67B by September. These astronomical figures are “unlike anything we’ve ever seen before in the history of commerce,” he said.
So with all the money that’s being poured into AI, what does this mean for data centers, which are being called the “largest financial bet in U.S. history?”
“As someone who's not an expert in AI or data centers, but just thinking about the magnitude of capital that needs to be deployed, the [electrical] power is not there,” Zelman said. “There seems to be a mismatch with power and the actual completion of the data centers.”
Appel said the actual “bubble” may not be on the compute side but rather on the power availability and supply side of things.
“The risk is getting the product online, getting it developed, getting the power access and dealing with local politics and different moratoriums,” he said. “There are still tons of new starts happening, but some will struggle.”
Subscribe to the Walker Webcast on YouTube for new episodes every week.
This article was produced in collaboration between Walker & Dunlop and Studio B. Bisnow news staff was not involved in the production of this content.
Studio B is Bisnow’s in-house content and design studio. To learn more about how Studio B can help your team, reach out to studio@bisnow.com.