A high-profile office property in the core of Center City may be heading for a distressed sale as the borrower and lender spar over a workout plan.

Four Penn Center has received a new valuation of $61M, down 34% from when JPMorgan Chase originated its CMBS loan in 2016, according to CMBS monitoring platform Morningstar Credit. The valuation is also below the $63.9M of senior debt the borrower owed as of April.
The loan entered special servicing in May after the borrower — an entity associated with Teresa Tsai and her firm, Treeview Real Estate Advisors — failed to pay it off by its maturity date.
The lender began foreclosure proceedings on July 20 after the owner offered to enter into a workout plan, according to commentary from the loan’s servicer, Wells Fargo. The borrower made "unacceptable demands” of the lender before the foreclosure proceedings commenced, the commentary says.
“Borrower stated that they are unable to pay the loan off without a substantial [discounted payoff], and are unwilling to spend any additional capital for leasing, operations or [capital expenditures],” it says.
“Lender will decide whether to pursue taking title through foreclosure, or pursuing a disposition by Receiver Sale if successful in getting a receiver appointed,” the servicer added.
Treeview and Tsai could not be reached for comment.
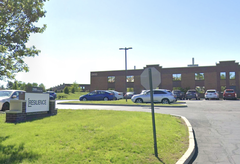
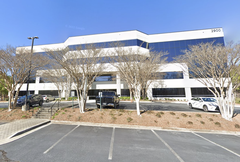
The 523K SF building, sitting one block west of City Hall at 1600 John F. Kennedy Jr. Blvd., was built in 1964 and renovated in 2001. It is 65% occupied, compared to the 84% the loan was underwritten for.
The lender is collecting rent, but cash flow is no longer enough to cover operational expenses, taxes and insurance, according to the servicer commentary.
Government agencies with long-term leases constitute nearly half of the building’s tenant base.
The U.S. Environmental Protection Agency is the building’s largest occupant with a 176K SF lease through March 2037, according to the servicer commentary.
The Philadelphia Municipal Authority holds another 53,600 SF through January 2040.
Morningstar predicted that the workout plan will conclude with a distressed sale. That outcome is likely due in part to the building’s tumultuous history, according to Morningstar Associate Managing Director David Putro.
“This loan has really had an up and down performance,” he said in an emailed statement. “It fell below breakeven even before the pandemic, bounced back a bit, fell back again.”
The loan entered a low-occupancy watchlist in 2018, and since then, its origination has been in a “cash trap” in which any excess revenue enters a leasing reserve account, according to the servicer commentary.
“I think the borrower is reading the still struggling market here and realizes that getting this building stabilized will be quite a heavy lift at the moment,” Putro said.
Across greater Philly, more than a third of CMBS office loans were categorized as distressed in January 2026, according to a Kroll Bond Rating Agency report.
That was the highest percentage of the 20 large metro areas included in the analysis, which saw a 13.8% distress rate in the sector on average.