The penny stock company aspiring to develop a $3.8B mixed-use district in Downtown Atlanta has disclosed a nearly $19M accounting error in a past earnings report that led the company to understate its financial liabilities.
Webstar Technology Group revised its 2025 annual earnings report in an Oct. 15 filing to reflect total liabilities of $19.8M, a correction from the $1.1M in liabilities it previously reported to the Securities and Exchange Commission. The company said it had mischaracterized a portion of its liabilities and noted that there was a “material weakness in internal control over financial reporting.”
The restatement comes after Webstar’s previous accounting firm, Pipara & Co., resigned on April 15 rather than signing off on an audit of the 2025 earnings, according to SEC filings. Webstar published its unaudited financials, then hired a new accounting firm that, according to Webstar, discovered the error after reviewing the firm’s historical financial statements and related accounting records.
“Webstar recognizes the significance of its historical accounting corrections, financial reporting deficiencies, and outstanding financing obligations,” Webstar CEO Ricardo Haynes told Bisnow in an emailed statement.
“We believe these matters should be evaluated in the context of the company’s publicly disclosed financial condition, its transition in business strategy, and the corrective measures being pursued by management,” he said.
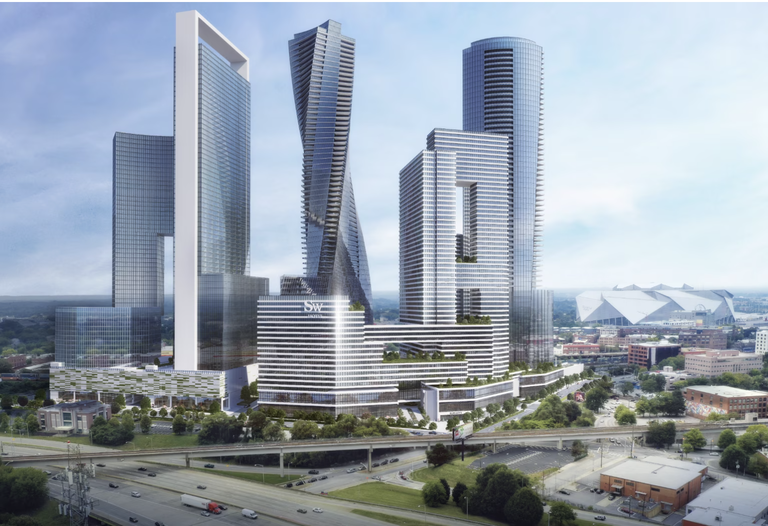
The revision is the latest red flag in Webstar’s history of errors and omissions in its public filings and raises more questions about its ability to secure the funding necessary to kick off Forge Atlanta, an 8.4M SF mixed-use development.
In the revised earnings report, Webstar also disclosed that it has not paid off the nearly $34M mortgage it took out to acquire the 10-acre site for the ambitious project, nor has it paid the fees it agreed to cough up to extend the loan past its original maturity in March.
The earnings revision sets off alarm bells, even for a startup like Webstar that recognized zero revenues over the past two years, said Preeti Choudhary, professor of accounting at the University of Arizona and an adviser to the Public Company Accounting Oversight Board, a nonprofit created by Congress to oversee publicly traded U.S. companies.
“That sounds very fishy,” she said.
Up until June 2024, Webstar was a software firm. Haynes, along with four partners, acquired control of the business through a $500K preferred stock deal and pivoted its strategy to resort and mixed-use development.
Webstar closed in December on the site at the corner of Ted Turner Drive and Whitehall Street SW, where it plans to build more than 2,300 luxury condo units, 600K SF of office space, 200K SF of data centers and more than 120K SF of retail, dining and entertainment space.
The company has been attempting to line up financing for the first phase of the project, a $756M endeavor that would include a 300-room hotel, 600 luxury condo units and 60K SF of retail and entertainment space. If it can deliver, Fulton County's development authority has agreed to give it a $10M tax break and $224M of bond financing.
But in April, Webstar revealed that it was at risk of going out of business after defaulting on the mortgage it took out to acquire the site. In its latest filing, it again raised doubts about its ability to get loans and other financial backers given the current economic climate.
“We expect that our current working capital position, together with our expected future cash flows from operations, will be insufficient to fund our operations in the ordinary course of business, anticipated capital expenditures, debt payment requirements and other contractual obligations for at least the next twelve months,” Webstar said in its amended report.
Haynes said in an email the company’s priorities include “establishing a viable project capitalization structure, and evaluating strategic alternatives for advancing Forge Atlanta.”
An Incomplete Takeover
The newly disclosed liability stems from the preferred stock deal that Haynes and the four partners reached to take over Webstar from its former CEO, founder and majority stockholder, James Owens.
In June 2024, Owens sold his preferred stock in Webstar for $500K, but more than a year later, $325K of that sum hadn't been paid, according to the company's SEC filings. After Owens filed for personal bankruptcy, the trustee charged with overseeing the liquidation reached a deal with Webstar's executives to complete the stock purchase.
The executives agreed to pay $297K for the preferred shares and paid a nearly $30K deposit to seal the deal. But the remaining $268K that the Webstar executives owe still hasn't been paid.
Haynes wrote in his response to Bisnow's inquiry that the company “recognizes the outstanding obligation and the legal considerations associated with Mr. Owens' bankruptcy estate.”
He added that Webstar is “evaluating available resolution alternatives, including potential modifications to conversion or settlement terms.”
Owens told Bisnow on Tuesday that he has no more stake in Webstar and that it’s up to the bankruptcy trustee as to how it will pursue the share conversion against Webstar.
Owens also said he was “not pleased” by Webstar’s current executive roster.
“I ran that company impeccably from its inception. I went through the front door of FINRA and the SEC, followed every rule, went through every qualification and kept it filing flawlessly for years,” Owens said. “I didn’t expect it to turn into this.”
In light of the accounting error, Haynes said Webstar management is “evaluating improvements involving technical accounting expertise, financial reporting procedures, transaction documentation, segregation of duties, and independent oversight.”
He said the company plans to use “qualified internal and external resources to strengthen these functions” but said it has not yet finalized specific hiring numbers or implementation dates.
Webstar’s new accounting firm, Victor Mokuolu CPA PLLC, was sanctioned and fined $30K in 2023 by the Public Company Accounting Oversight Board for failing to disclose connections with other accounting firms, according to a press release at the time. In September 2024, the Texas State Board of Accountancy ordered that Mokuolu be reprimanded and levied a more than $15K fine against the firm, according to the order obtained by Bisnow.
Haynes said Webstar hired Victor Mokuolu in April 2026. He said Webstar is “reviewing the relevant licensing history and its implications, if any, for the firm’s eligibility to perform the company’s engagements.”
“We will not speculate about the significance of historical licensing matters without examining the underlying regulatory record,” Haynes said. “The company takes the professional qualifications and regulatory standing of its independent accounting firm seriously.”
Loan Still Unpaid
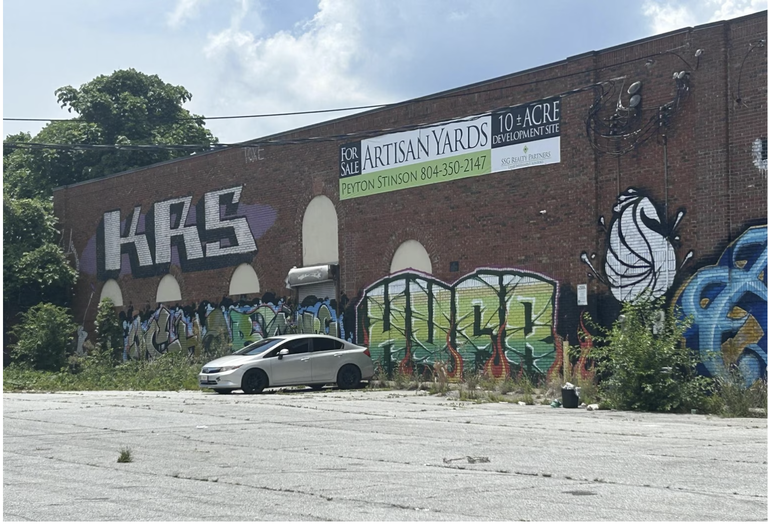
Webstar bought the 10-acre site for $34.5M with a $33.7M loan from an entity controlled by Atlanta food magnate Russell McCall, who was also the property's seller. Webstar acquired the land through a subsidiary called Forge Atlanta Asset Management LLC, of which it owns 90%, while joint venture partner Urbantec Development Partners owns 10%.
Urbantec, led by CBRE broker Jae Kim, hatched the original plan for Forge Atlanta but lost the site to McCall through foreclosure in 2023.
The loan was originally set to mature in March, but McCall gave Webstar’s Forge Atlanta entity an extension through April and again until Oct. 1.
Webstar agreed to pay more than $1M in additional payments and fees to extend the loan but hasn't paid more than $600K of that total, according to SEC filings. The loan's extended maturity date has passed, but McCall hasn't declared Webstar in default, Jerome Zivan, an attorney representing McCall, told Bisnow in an email Tuesday. He declined to comment further.
Choudhary said Webstar’s lack of payments is a strong indication that the firm has struggled to gain outside investment interest from banks or other major lending institutions.
“It sounds like the only way they borrowed money from the seller is because they can’t get money from a third party,” Choudhary said. “This is like lending my teenager money. You have no job, no credit rating, and you want to borrow money.”