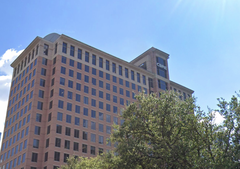
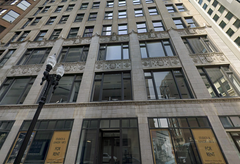
After executing five one-year extensions, Park Avenue-based real estate investment firm Savanna has run out of time to pay off a nearly half-billion-dollar loan tied to a Midtown Manhattan office tower.
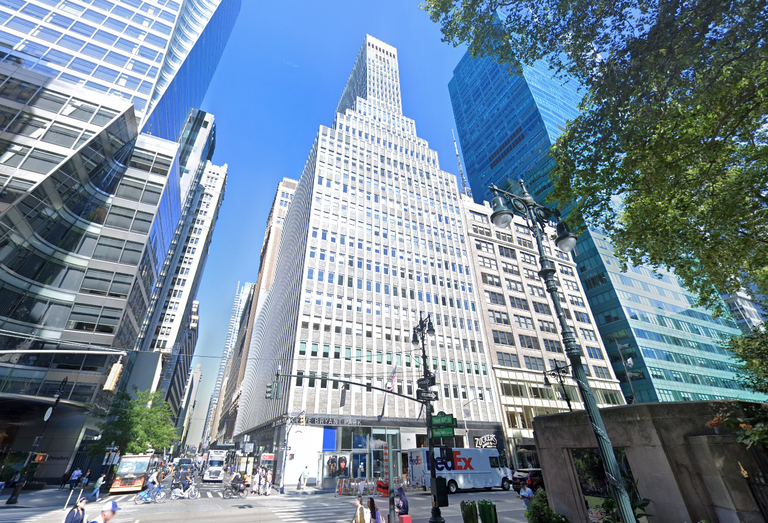
The $463M CMBS loan tied to 5 Bryant Park matured on June 8. Savanna failed to make the required balloon payment, according to a report from CMBS tracking firm CRED iQ.
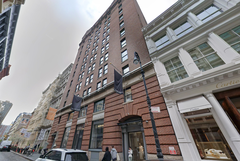
Savanna took out the loan in 2018 to finance its $640M purchase of the 34-story Midtown Manhattan tower from Blackstone. While the loan was initially scheduled to mature in June 2020, it also came with five one-year extension options. All of those have been exercised.
The 683K SF building on Sixth Avenue was 81% occupied at the end of March, according to servicer commentary on the Morningstar Credit database. Its net cash flow has fallen more than 20% from the debt's underwriting, according to Morningstar Credit Analytics Senior Vice President David Putro.
Interest payments and operating expenses have both increased, and the debt is now underwater, Putro said.
Savanna didn't immediately respond to a request for comment.
The loan has been on a watchlist due to the drop in its net operating income. Savanna has been in talks with the loan's master servicer and hopes to have a refinancing deal in place within 90 days, according to commentary posted early last month.
S&P Global downgraded three classes of the CMBS debt in September, including the $200M top-rated class, which it lowered from a AAA rating to AA. Part of the lowered rating was because tenants occupying 45% of the building are due to have their leases expire between 2027 and 2029.
The loan on 5 Bryant Park is the second tied to an office building in the neighborhood that Savanna had trouble refinancing. It defaulted on a $242M loan at 521 Fifth Ave. last year, which was transferred to special servicing. Wells Fargo sued to foreclose on the building in November.
Wells Fargo won a default judgment in that case in May, according to court records. A New York State Supreme Court judge appointed a referee to coordinate a possible foreclosure sale.
While Savanna has been reckoning with upside-down capital stacks on its prepandemic office acquisitions, it is also back in the role of aggressor. It bought 799 Broadway in Midtown South last year for 4% below the value of the building's debt. It also has begun construction on a luxury condo tower in West Palm Beach after landing a $380M construction loan in March.