The vast majority of the office CMBS loans that come due this year will have problems at refinancing, according to a new study, as questions over asset values in a heightened-rate environment continue to plague the industry.
A total of $7.8B worth of fixed-rate CMBS loans on offices will mature this year, and Moody’s Analytics data suggests about 84% of them will face challenges when their borrowers seek to refinance, Commercial Observer reports.
“Ultimately, not all of these loans that are in this 84% will default or be liquidated,” Kevin Fagan, the head of CRE economic analysis at Moody’s Analytics, said during the firm's first-quarter economic discussion. “Some owners will find new equity to save quality assets, and some borrowers will get extensions and workouts as we work through this down cycle … but we certainly expect the maturity wave of offices to add some pricing clarity on how offices that have to be forced-sold into the market will be priced by opportunistic investors."
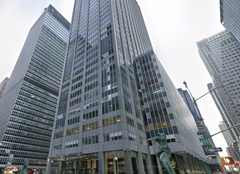
Last week, the largest maturing CMBS office loan that was set to mature in New York City this year, a nearly $1B loan on RFR's Seagram Building on Park Avenue, was able to secure a multiyear extension. RFR had been seeking a $1.1B refinancing package, but its inability to find a deal, necessitating an extension, reflects the challenges for borrowers with debt maturing this year.
Office vacancy across the country hit 19% in Q1, per Moody's, which is an almost 30-year high. Moody’s predicts office values will drop by 25%, a downward trend that will continue through the rest of the year, per CO.
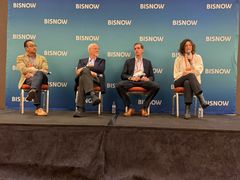
“This is a period which is not unlike the mall space five years ago,” Trepp Senior Managing Director Manus Clancy said on Bisnow's podcast this week. “In many ways, I think the outcomes will be quite similar.
“The level of defaults will be significant, there will be properties valued at half today than they were 10 years ago, losses will be felt not only in the equity side but on the debt side. The one part of the equation that has yet to be really told yet is in 2018 to 2022, mall owners really dug in and fought to keep their properties. We don't know what the behavior of the office owner will be yet. That part of the story remains very fluid.”