Fannie Mae and Freddie Mac, the government-sponsored enterprises that guarantee a huge sum of home and multifamily loans, have a growing list of condominium buildings, associations and co-ops that they won't lend to, the Los Angeles Daily News reports.
These lists are secretive, with condo associations and sellers only finding out they are on the list when in talks to sell a unit, which have put pending deals at risk and forced buyers to pursue more expensive mortgages. A spokesperson for Fannie Mae told the Daily News that the list includes 1% of the nation's condos and co-ops.
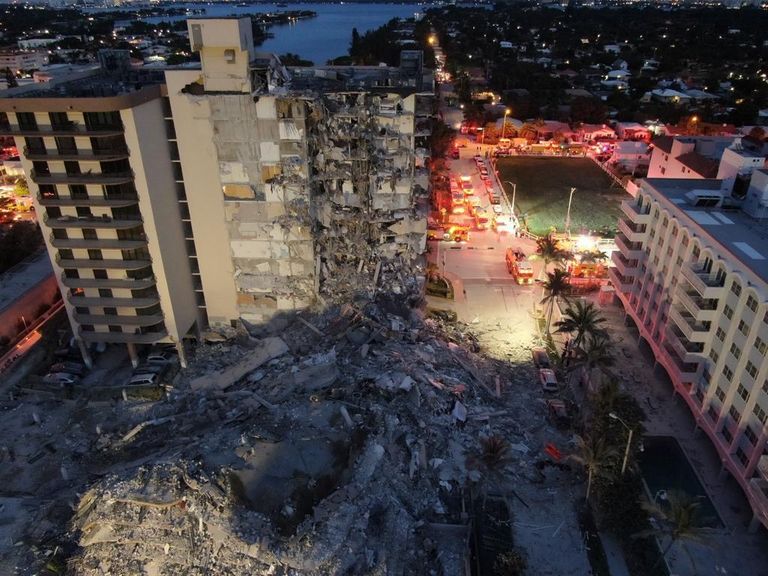
Orest Tomaselli, the president of Philadelphia-based condo and co-op lending service provider CondoTek, told the Daily News that the blacklist of condo and co-op buildings has grown to more than 1,400 properties from 900 in the 16 months since standards were tightened after the Champlain Towers South collapse in Surfside, Florida, which saw 98 people killed and $1B in property losses.
Now both lending giants are weeding out condos and co-ops experiencing deferred maintenance, structural issues or a lack of financial reserves or insurance to cover future repairs, the Daily News reported.
The only entities with access to the lists are lenders and servicers, according to the paper, leaving buyers and sellers only aware they may be on the list when in the process of a transaction.
“It’s a crapshoot. The only way for you to find out if a [condo] project is on that list is if you apply for a mortgage and the lender runs that project to see if it’s unavailable. And only then, typically, is the buyer informed,” Tomaselli told the paper.
A mortgage broker told the Daily News the GSEs are "essentially blacklisting" the communities, forcing buyers and sellers to accept riskier, higher-cost mortgages.
In response to the tightened requirements, the Mortgage Bankers Association and the National Association of Realtors called for Fannie and Freddie to overhaul and clarify their homeowner association questionnaire.
Fannie and Freddie — which buy and back conventional mortgages made by lenders — are building the list around an updated set of questionnaires sent to HOAs, the Daily News reported, and lenders must also engage in more robust due diligence on properties or co-ops, reviewing six months of HOA meeting minutes and diving into inspection and engineering reports made in the past five years.
The list adds another complication for condo and co-op owners in the wake of the deadly Surfside collapse. Property insurance bills have also spiked, and many condo boards in South Florida have decided to terminate and sell their buildings to a developer rather than pay to bring their properties up to safety standards.