Retail, Office Loans Dominate The $6.7B In CMBS To Mature This March

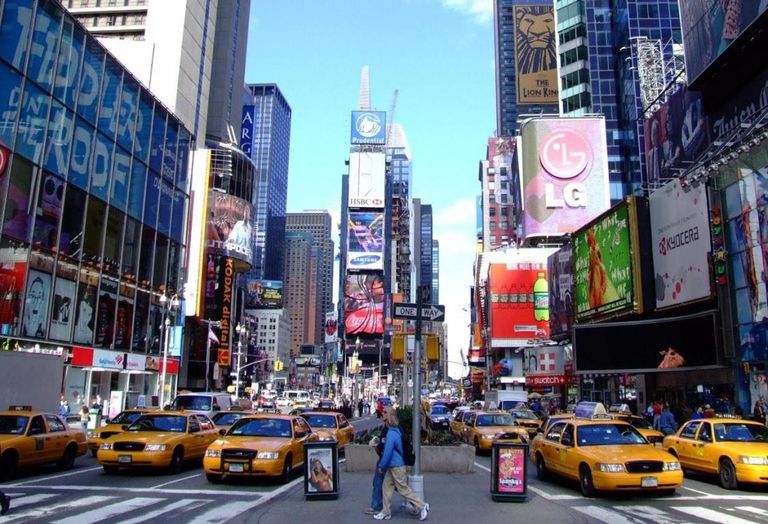
Times Square

Of the $61.1B in commercial mortgage-backed security debt set to mature within the next six months, $6.7B is due in March.

Most of these loans were issued in the late stages of the commercial real estate bubble, either in 2006 or 2007, and with the current tightening of banks it is unclear whether many of these properties will meet today’s credit standards.

Office loans make up 28.9% of the debt while retail loans account for 26.5%, according to the latest Trepp report.

More than 9.7% of the CMBS debt to mature in March is in default and 14.2% has been transferred to special servicing. A $1.1B loan for 5 Times Square in Midtown Manhattan is the largest CMBS loan set to mature this month, and tenant Ernst & Young rents most of the building under a lease that ends in 2022.

Many experts are worried that retail closures could seriously hurt the economy should these companies fail to make their loan payments. Adding to that fear, JC Penney recently announced store closings that put almost $7B of CMBS loans in jeopardy.
Continue reading this story with a free account

Log in or register
Sign up for more articles like this
Subscribe to Bisnow's National Newsletters
Related Stories

Meta's Soaring Data Center Emissions Force It To Reconsider Climate Goal

The Children's Place Hires Adviser To Sell 509 Store Leases, Distribution Center

Senate Passes Bill To Speed Up Permitting, Make Data Centers Pay More

Trepp: 20% Of The CMBS Loans Modified Since 2022 Are Delinquent Again

INSIDE THE SPACE: A Luxury Salon Suite Concept Expands Nationally

Moinian Group Returns To Israeli Bondholders For Capital In NYC, Miami

191 Peachtree Loan Moves To Special Servicing After Banyan Misses Maturity

Anthropic's Record IPO Reverberates Across Data Center Sector

Brookfield's Lowell Baron On Building The Firm's Edge, Where It's Betting Next

Brookfield Bets $110M On Resorts Company Rolling Up Independent Campgrounds

KFC Operator Is Latest Casualty In Wave Of Fast-Food Franchisee Bankruptcies

Target To Spend Up To $6B On Store Upgrades, Openings As Sales Accelerate