
The Federal Reserve might have raised interest rates by 25 basis points on Sept. 16 to hedge against inflation, but the Fed is now dealing with the consequences of having kept rates too low for too long, says Sean Dobson, CEO of Amherst, one of the largest owners and operators of single-family rental properties in the U.S.
“In terms of the overall economy and what the Fed's trying to do, we think they're late, and they've been late for about seven or eight years,” he said on this week’s Walker Webcast hosted by Walker & Dunlop CEO Willy Walker. “They were late in taking away the subsidies post-Great Financial Crisis, they kept rates too low for too long, and then when Covid came around, they had a chance to let things settle back in and didn't.”
Taking this approach, Dobson argued, led the Fed to overease and keep interest rates at a level that was “never seen before” relative to economic activity. As a result, he said housing takes the brunt of those mistakes, both in monetary and fiscal policy.
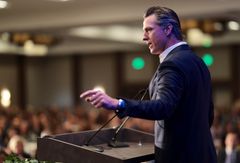
“Raising rates today is fighting inflation that was caused a couple of years ago, and we don't need to keep inflating it,” Dobson said, speaking from the stage of the 2026 Zelman Housing Summit.
He added that housing prices today may be more expensive than 20 years ago, prior to the GFC, but that doesn’t mean prices are necessarily going to take a huge tumble.
In 2008, he said, there was a clear gap in the market. Home prices hadn’t necessarily overrun fair value, but many were financed with promotional rates and payment schedules with limited durations. This was the main factor that created a glut of supply.

“Teaser payments were going to expire, adjustable-rate mortgages were going to be reset, people had the option to not pay the interest, so all the tricks to get the monthly payment to be small relative to the loan balance had temporary features to them,” Dobson said. “You could just forecast when the music was going to stop.”
The housing market in 2026, however, paints a different picture. In the wake of Covid, instead of a flood of houses hitting the market, the opposite has happened, with an estimated shortage of almost 5 million housing units.
“[Covid] was either going to be the Spanish Flu, in which case, 30% to 35% of the population was going to die in a matter of months, or it was going to be what it was, a nonevent,” Dobson said. “We took rates to 3%. When we did that, not only did we create more buying power per unit of monthly payment that manifests itself into asset price inflation, but we took those homes off the market for a long time. I'd say it's tantamount to burning them down.”
The real issue in today’s housing market is not how many homes there are, but how many homes are tradable — perfectly illustrating the “lock-in effect” that comes up frequently in the housing conversation across the U.S., he said.
“I think that you can't overstate the impact [the lock-in effect] has on keeping home prices unsustainably high,” Dobson said. “Home prices are high for technical reasons, not because of fundamental reasons.”
Amherst, he said, isn’t in the single-family space but owns and operates approximately 47,000 SFR units across 32 markets and has $17B of assets under management. After the GFC, Amherst believed that banks had learned their lesson and were not going to give out subprime mortgages again. This meant there would be a new customer in the housing market that was going to be renting for a long period of time instead of owning, he said.

But, at the time, this was a small, fragmented industry — a stark contrast to the multifamily industry. Amherst built its SFR platform from scratch to get to where it is today, he said.
“We built our platform from the ground up, and that's why the U.S. is the greatest economy on the planet, because you could build it from the ground up,” Dobson said.
In spite of its success in the SFR space, Amherst isn’t leaping into single-family or multifamily assets because the firm remains optimistic that SFR will continue to grow and become a major force in the housing space, Dobson said.
“This is a new sector that will be larger than almost all of commercial real estate combined,” he said. “In the residential space, there's $9T of outstanding and first lien mortgages, but the market value for single-family homes is $55T. [An] ecosystem that allows a large investor to responsibly deploy capital in scale into an asset class that big is a remarkable thing.”
Additionally, Dobson gave Walker his list of “wheres and where-nots” of places that his firm is, or isn’t, eyeing for investment.
Amherst has a large presence in Texas, Florida, Georgia and North Carolina, so the Sun Belt will continue to be an area of interest for the company. Market dynamics in states such as California, parts of Pennsylvania, particularly Pittsburgh, and Northeast Virginia are not as conducive to Amherst’s business model.
Walker and Dobson also discussed the housing market’s biggest concern moving forward: stagflation, when inflation is high while the economy is weak.
“Stagflation is a destroyer of wealth for almost whoever you are,” Dobson said. “If the Fed keeps trying to fight three years ago's inflation, they run a real risk of stagflation. If oil prices go up, interest rates go up and incomes go down, the chance of this situation playing out has tripled within the past couple years.”
Subscribe to the Walker Webcast on YouTube for new episodes every week.
This article was produced in collaboration between Walker & Dunlop and Studio B. Bisnow news staff was not involved in the production of this content.
Studio B is Bisnow’s in-house content and design studio. To learn more about how Studio B can help your team, reach out to studio@bisnow.com.