Oceanwide Holdings has been forced to hand over the keys to its most prominent San Francisco project.
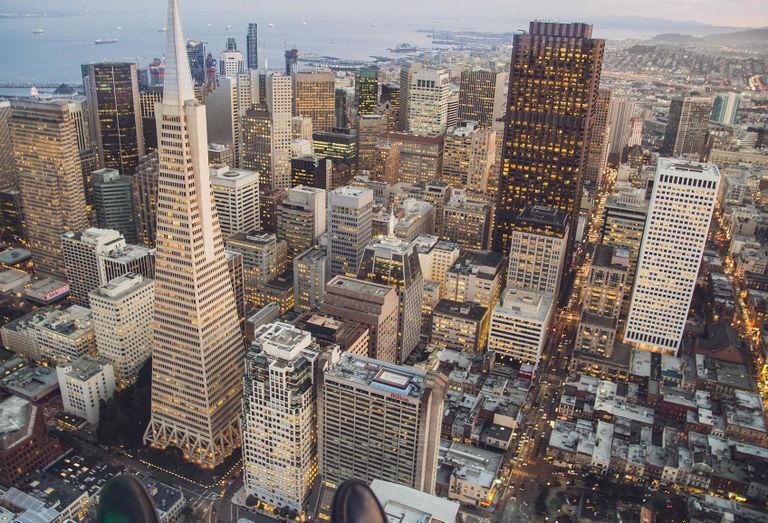
Creditors have taken over the stalled 2M SF Oceanwide Center after subsidiaries of the beleaguered Chinese developer missed payments of notes worth $321.5M, according to the San Francisco Business Times.
The property at Mission and First streets is slated to become the second-tallest tower in the city. Construction at the site halted last year, and two potential deals to trade the asset for $1B and $1.2B, respectively, fell through during the coronavirus pandemic.
The forfeiture is the latest sign of struggle for Chinese developers as the country’s largest property developer, Evergrande, continues to head toward implosion with over $300B in debt.
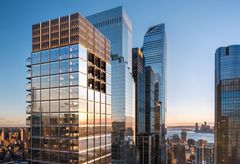
Elsewhere in California, Oceanwide has paused construction work at the $1B Oceanwide Plaza project in Los Angeles after unpaid work claims. In New York, Oceanwide is looking to offload its development site at 80 South St. for $190M, a far cry from the $390M it paid The Howard Hughes Corp. in 2016. That building was slated to become the tallest in New York City.
Those two assets could face a similar fate as the San Francisco tower if sales agreements aren't reached. The projects could be completed by some of the country's biggest developers, such as Brookfield Asset Management, Related Cos. and Hines, but only Hines has acknowledged considering making a deal.
In July, a handful of the top executives at Oceanwide, including CEO and Executive Director Zhang Xifang and Board Chairman Song Hongmou, resigned. The shakeup came after the firm sold $340M worth of assets to Sunac Real Estate Group Co., a major property developer headquartered in Tianjin, China, in an attempt to free up capital, according to the San Francisco Business Times.
Evergrande’s financial woes largely came about last year when President Xi Jinping set a policy ordering real estate companies in China to reduce their debt. Oceanwide isn’t the only firm to see ripple effects, with about 20% of Chinese development companies at risk of defaulting on bonds sold to international investors.