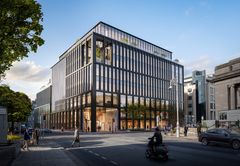
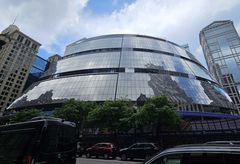
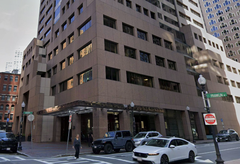
Blackstone has completed a modification on a $195M loan tied to the San Francisco property known as the Schwab building at 211 Main St., officially removing it from special servicing and returning the loan on the 417K SF office tower to its master servicer, Kansas-based Midland Loan Services.
The total debt stack includes three subordinate notes totaling $25M, according to a recent Morningstar newsletter.
After Blackstone defaulted on the maturity, the 17-story asset went to a special servicer in the first quarter. Blackstone was granted a four-year extension, pushing the maturity date to April 2028.
Blackstone didn't respond to a request for an interview by press time.
The property was once fully occupied by Charles Schwab Corp., but the financial services firm downsized to about a third of its original presence to occupy 170K SF on six floors, according to Morningstar.
The property is fully leased to Schwab through April 2028 but is available to other tenants via sublease.
Schwab is planning to move its headquarters to Westlake, Texas, but has not decided what footprint it will maintain in San Francisco in the long-term.
“We want to be clear that San Francisco remains an important Schwab employment center, and we expect to continue employing local talent to support our clients and maintain our special culture of stewardship within the community,” a Schwab spokesperson told Bisnow.
David Putro, senior vice president and sector lead for Morningstar Credit Analytics, said the building’s tenancy future is up in the air.
“No word on how the tenancy plays out,” Putro told Bisnow. “It might take a bit of time since Schwab has a lease still in effect, so the owner might be limited as to what they can do in the interim.”
In April, a spokesperson for Blackstone said this is par for the course.
“This is a procedural step needed to effectuate a change to the term of the loan, which requires approval from the special servicer,” the spokesperson said.
“This building is 100% leased to a high-quality, credit-worthy tenant through 2028.”
In recent years, Schwab has implemented layoffs across the company. Approximately 2,000 employees were laid off last November.
SFGate reported that Schwab slashed up to 6% of its workforce at that time and shrunk its real estate footprint nationwide to reduce operating costs.
UPDATE, SEPT. 5, 8:56 A.M. PT: This story has been updated with a statement from Charles Schwab.