A pair of luxury towers in Chelsea has signed one of New York City’s biggest financing deals of the year so far.
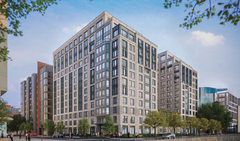
One High Line, two towers next to tourist hub The High Line and located at 500 W. 18th St., has scored a refinancing loan worth nearly $1.2B from a JPMorgan Chase-led group of investors, Bloomberg reported.

The senior loan came from JPMorgan, while Tyko Capital — a private equity and private credit investment manager with backing from Elliot Investment Management — provided mezzanine debt. Brokers from Walker & Dunlop arranged the financing.
Witkoff, Access Industries and Monroe Capital have owned the development since 2021, when they bought it out of foreclosure and half-finished from Nir Meir’s HFZ Capital Group.
The refinancing deal is among the largest nationally to be backed by a single asset this year, Bloomberg reported.
It also takes place against a backdrop of a steadying NYC condo market. That market’s stability is relatively new: Condo sales in Q2 2023 were down 30% from a year prior, per numbers from Brown Harris Stevens Development Marketing.
But even when the overall market wasn’t doing so well, condo sales at One High Line were some of the standouts, Brown Harris Stevens noted at the time.
Since then, NYC’s luxury condo market has picked up steam, beating pre-pandemic averages for sales volume in Q2 this year, a Marketproof analysis shows. One High Line continued to sign noteworthy deals that month, including May’s most expensive condo sale of a $13.7M four-bedroom unit, Mansion Global reported.
Witkoff co-CEO Alex Witkoff told Bloomberg that a highly anticipated interest rate cut from the Federal Reserve will likely boost the towers further.
“Lower interest rates do benefit housing,” he said. “We’re quite bullish that not only will our pace of sales be sustained, but that it’ll even be picked up.”
The towers appear to be turning around a troubled history. HFZ paid a record price for the land in 2015, but faced multiple lawsuits from its lenders after running out of cash, per Bloomberg. More than $800M in sales have taken place since then.
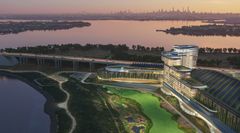
The development, previously known as The XI, has two towers that twist gradually away from each other and was finally completed earlier this summer, Surface Magazine reported.
The towers now reach 36 and 26 stories, totaling 241 units plus a hotel portion from hotelier Alan Faen that is expected to open next year.