Senior living and healthcare REIT CareTrust has bought a portfolio of UK care homes for £1.1B, the latest humungous deal by a U.S. investor in the sector.
New York-listed CareTrust bought the 2,970-bed portfolio from care home developer and operator LNT in a deal that will take its UK portfolio to £2.9B and more than 12,000 beds, after buying into the country last year.

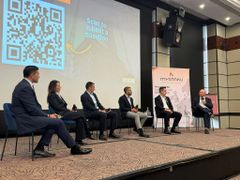
“My experience of American capitalism is that it's way more efficient than UK capitalism,” CareTrust REIT Senior Vice President of Investments Martin Robb told Bisnow’s Later Living Conference on Sept. 29, before the acquisition was announced. “The fundraising capability is impressive.”
Robb was a director at Care REIT, which CareTrust bought for £634M last year in its debut UK deal.
He said access to more liquid and efficient capital markets gives U.S. buyers an advantage over UK and European peers.
“They’ve shown they’re willing to come over here and invest to grow,” Robb added.
CareTrust’s UK portfolio had grown in size by 50% even before the LNT acquisition.
Its total portfolio size after the deal will be $11.5B (£8.7B), and its market capitalisation is $8.6B.
Robb said CareTrust is willing to restructure portfolios so deals benefit both the operators of care homes and the owners of their properties, and that is evidenced by the structure of the LNT deal.
CareTrust is buying the portfolio in two tranches: First, it is paying £576M for a portfolio of 24 homes that have already been completed. It will pay £504M for the remaining 21 homes and buy them as they are completed throughout 2027.
All of the homes will be leased to Crystal Care, LNT’s care home operating company. When sales complete, the properties will be leased to Crystal Care on 20-year triple-net leases with a 3% annual uplift while they lease up, a period that CareTrust expects to last between two and four years. Each home will pay annual rent of £1.4M.
Once assets are fully leased and stabilised, the homes will be transferred to a REIT Investment Diversification and Empowerment Act structure, which allows a REIT to share in the operating income produced by a care home.
CareTrust said this two-phase structure allows it to have guaranteed income during the lease-up phase and to take advantage of increased operating income once homes are up and running. It means the portfolio should make a 7% yield once it is fully operational.
The deal will push CareTrust’s UK income from £74M to £171M, on the assumption that each asset produces £2.15M of income.
The portfolio being bought from LNT — which has been building care homes in the UK for more than 30 years and has developed more than 270 properties comprising nearly 18,000 beds — comprises 2,970 units spread across the country.
Roughly 42% of the homes are in the south of England, 27% in the Midlands, 11% in the north west and 9% in the east of England, with the rest spread around the country.
Robb said the areas outside the wealthy south east have the greatest need for new units, but the economics make it hard to put money into such areas.
“We own stock in poorer parts of the country as well, where there is deprivation and there is genuine need,” Robb said. “So there's that sort of existential question of actually how do you make that work? ... We would like to invest in deprived areas as well if we could figure out how to do it.”
Senior living is attracting significant amounts of investment in spite of the wider malaise in UK investment markets.
Partly, that is the well-known, long-term demographic trend of an ageing population, which supports demand for assets.
But some investors are willing to buy senior living assets at yields below those of government bonds because of the nature of inflation-linked leases.
“In the last three or four weeks, I've bid on three opportunities sub-5%, which is ultimately below where gilts are currently sitting,” JLL Director Verity Knight said at the event.
“Certain investors still do really see value long term in this market, and they're obviously not struggling to underwrite exit yields much keener than where they're entering.”